

















In this second of four linked articles, Adam Cole, Retirement specialist at Quilter looks at the position for clients who have had one or more benefit crystallisation events under the previous Lifetime Allowance (LTA) regime.
When working out the available Individual Lump Sum Allowance (ILSA) or Individual Lump Sum and Death Benefit Allowance (ILSDBA) you can either use:
- the standard transitional calculation or
- apply for a transitional tax-free amount certificate (TTFAC) and use that instead.
Note: Clients should not automatically apply for a TTFAC, as it could produce a worse outcome than the standard transitional calculation. Once issued, the TTFAC is binding and cannot be revoked. Calculate both options before applying.
The examples below explain how each calculation works.
Standard transitional calculation
Note where a client has used up 100% of their LTA, there is no available ILSA or ILSDBA under the standard transitional calculation.
The standard transitional calculation consists of two steps:
1. Calculate the monetary amount of LTA previously used up in the same way that you would if you did the calculation on 5/4/24. This means:
2. for people with no protection, enhanced protection and lifetime allowance enhancement factors, apply the percentage of used LTA against £1,073,100
3. for people with Fixed or Individual protection apply the percentage of used LTA against their personal LTA
4. for people with primary protection, any crystallisation prior to 6/4/2014 should be revalued with the formula (crystallisation amount x (£1,500,000/LTA at date of crystallisation)). Any crystallisation after 5/4/14 you can apply the percentage of used LTA against £1,073,100
5. any amount crystallised at age 75 is disregarded (although the client will need to request an age 75 disregard) unless the client has taken tax-free cash (via a pension commencement lump sum, serious ill health lump sum or an uncrystallised funds pension lump sum) between age 75 and 6/4/24*
*Clients who have taken a tax-free lump sum after age 75 could benefit from a TTFAC if eligible.
1. Deduct a portion of this monetary amount from ILSA and ILSDBA
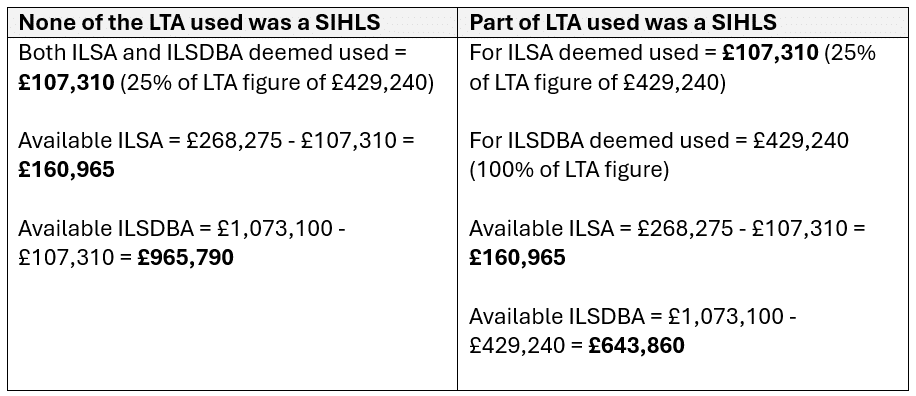
2. For ILSA – deduct 25% of the monetary amount from ILSA
3. For ILSDBA you deduct either:
- 100% of the monetary amount if a serious ill health lump sum (SIHLS) or lump sum death benefit of any size has been taken before age 75, or
- if neither of those have been taken, deduct 25% of monetary amount from ILSDBA.
Example
You have a client with a BCE statement showing an LTA utilisation figure of 40% (which equals a monetary figure of £429,240). They decide to take further pension benefits after 6 April 2024.
Transitional tax-free amount certificate (TTFAC)
Instead of the standard transitional calculation described above the member may seek a TTFAC.
A TTFAC helps clients, who received less tax free lump sums than the assumed amount under the standard calculation, to record ILSA and ILSDBA usage based on actual tax-free lump sums received before 6 April 2024.
A client can request one from any scheme they belong to, provided they can evidence all previous benefit crystallisation events (BCEs). If the evidence is insufficient, the scheme can refuse to issue the certificate.
There are a number of factors to consider around TTFAC so we have produced two related articles for Professional Paraplanner which go into further details around this, and they will be published in the coming days.
Let’s look at a simple example where a transitional tax-free amount certificate would give a client more tax-free cash than the standard transitional calculation.
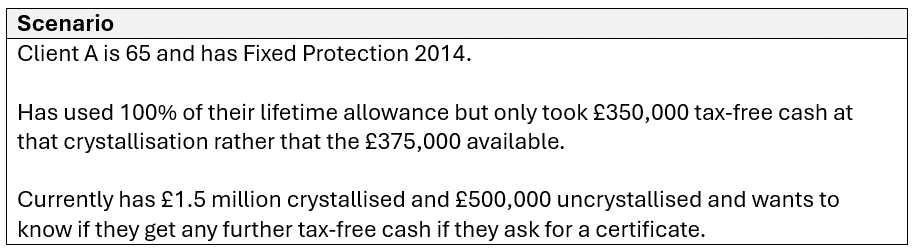
Under the standard transitional calculation, as 100% of the LTA has been used up, there are no available allowances. This means the remaining £500,000 when crystallised will not provide any further tax-free cash.
Under a TTFAC, ILSA used is £350,000 and ILSDBA used is £350,000.
As this leaves £25,000 remaining ILSA, the client could crystallise their remaining £500,000 and take £25,000 tax-free cash.
Application deadlines for TTFAC:
- For clients: The deadline to apply for this certificate is before the first relevant benefit crystallisation event after 5th April 2024.
- For Legal Representatives of deceased clients: If no relevant lump sum was taken while the client was alive, the deadline for a legal representative to apply for this certificate is 31st October following the end of the tax year in which the relevant lump sum death benefit is paid.
Where a scheme issues a TTFAC it will show the ILSA and ILSDBA amounts used up. Clients will need to provide this to pension schemes in the future when they take further lump sums.
Help with comparisons
Determining whether a client would benefit from a TTFAC is not always straightforward. Quilter’s transitional regime calculator can help you compare both approaches and assess which option delivers the best outcome for your client.
Main image: calculator, jakub-zerdzicki-Z4kCtJKCP34-unsplash