

From Ancient Rome to today’s retirement market, annuities have evolved considerably. However, Sebastian Van Mook, Business Development Manager at Standard Life, says that some of the assumptions surrounding them have changed far more slowly.
Few retirement products can trace their origins as far back as the annuity.
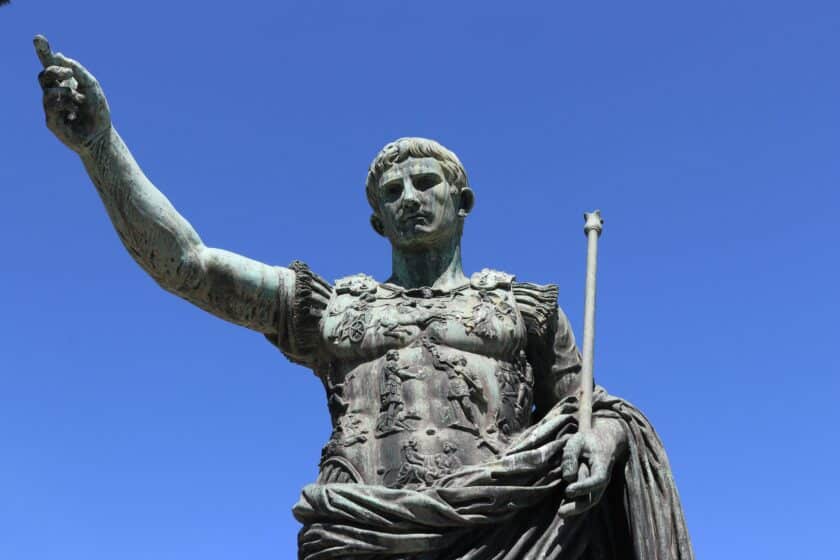
In chatting with Sebastian, and after a little historical digging of our own at Professional Paraplanner, we discovered that annuity-style arrangements can be traced back more than 2,000 years to Ancient Rome, where contracts known as ‘annua’ provided a regular stream of income in return for a capital payment.
While the modern annuity looks very different, the underlying principle of exchanging capital for a predictable income has endured for centuries.
What has changed significantly, however, is the product itself.
The annuity market has evolved alongside changes in retirement and the wider financial planning profession, and client expectations have evolved too.
In Sebastian’s view, that disconnect helps explain why annuities continue to carry baggage from a very different era.
Thinking back, he says: “Annuities became the swear word.”
The label stuck for a long time, even as the products themselves continued to evolve.
A reputation that lingers
Perceptions of annuities were shaped during a period when conversations frequently centred on value for money, flexibility and what would happen if the client died early.
Yet modern annuities offer a much broader range of options than many people realise.
One example is the level of protection that can now be built into a policy.
Sebastian points to features such as value protection, guaranteed benefits and spousal protection, noting that they can also be combined to reflect individual circumstances.
“You can combine them as well.”
That means conversations around beneficiaries and legacy planning can be more nuanced than some of the traditional assumptions surrounding annuities might suggest.
When old habits remain
The challenge is not simply that some long-held perceptions remain.
Sebastian also believes established practices can sometimes continue long after products have evolved.
He looks at guaranteed periods as an example.
Historically, five-year guarantees became commonplace. While there is nothing inherently wrong with that approach, he still encounters cases where the same option appears to be selected almost by default.
“We’re still seeing guarantee periods for five years,” he says.
Rather than questioning the recommendation itself, Sebastian believes this highlights the importance of ensuring product features are aligned to the individual client sitting in front of the adviser.
As he puts it: “You’d have to question what conversation actually happened there with the client.”
The broader point is that recommendations should be driven by client circumstances rather than convention.
Starting with the client
One story that has stayed with Sebastian involved an adviser requesting more than 140 variations of the same annuity quote.
What surprised Sebastian was not the amount of research being undertaken, but what it suggested about the process that had taken place beforehand.
“That tells me there hasn’t been a conversation.”
Research is an important part of the advice process but he questioned whether enough decisions had already been made about what the client was actually trying to achieve.
“What’s right for the client?” he asks.
In Sebastian’s view, understanding family circumstances, priorities and intended outcomes should naturally narrow the field long before hundreds of quote variations are required.
The most effective annuity discussions often begin not with product features, rates or provider comparisons, but with a clear understanding of the individual client’s objectives.
More than a product
This is one reason Sebastian often avoids leading with the word “annuity” altogether.
“I start with guaranteed income and I don’t mention the word annuity until later.”
The language may seem like a small point, but it reflects a wider shift in retirement planning.
Rather than beginning with a product, discussions increasingly start with the outcome a client is hoping to achieve.
And while annuities have evolved significantly over the years, the questions clients are trying to answer remain remarkably familiar.
How much income will I have?
Can I rely on it?
Will it last?
A product shaped by time
More than 2,000 years have passed since the Romans’ annuity-style arrangements.
Over that time, retirement has changed beyond recognition. Financial planning has become more sophisticated, client expectations have evolved and annuity products have adapted along the way.
What may not have changed quite as quickly are the perceptions that surround them.
For paraplanners and advisers alike, perhaps the lesson is a simple one. Modern annuities should be judged on what they offer today, rather than on assumptions formed many years ago.
After all, while the Romans may still recognise the basic principle of exchanging capital for a regular income, they would probably be surprised by the range of features and protections available today.
Despite all that innovation, some of the assumptions surrounding annuities have proved much slower to evolve.
Main image: clemens-van-lay-YT5DU0icZUA-unsplash