Ahead of November’s US midterm elections, George Brown, senior economist at Schroders, explores how different political outcomes could influence the country’s debt trajectory and shape market sentiment towards US assets and the dollar.
Our earlier paper assessed the likelihood of Democrats retaking not only the House of Representatives but also the Senate. In any view, we see a likely end to the Republican trifecta (control across both houses in addition to the White House). Divided government seems a certainty.
Although we expect the likelihood of fiscal consolidation to remain low even under divided government, markets are unlikely to reach that conclusion immediately.
Instead, the dollar may weaken initially as investors judge that a lower likelihood of fiscal stimulus implies weaker growth and narrower rate differentials.
But if Treasury yields subsequently rise, as we expect they will, the implications for the greenback become much less straightforward.
The dollar’s relationship with Treasury yields
Historically, rising US yields relative to the rest of the world have tended to support the dollar. But not all yield increases are equal.
Rises driven by stronger growth or higher rate expectations have generally been supportive. A rise driven by higher term premia and concerns over fiscal sustainability may have the opposite effect.
The more important question is not whether the dollar loses its reserve currency status. It is whether foreign investors remain as willing to finance growing US fiscal and external imbalances.
The US continues to run sizeable fiscal and current-account deficits, while foreign allocations to US assets remain elevated.
Even modest changes in investor behaviour could therefore generate meaningful currency flows. Foreign equity investors, in particular, remain lightly hedged against dollar weakness.
The implication is that higher Treasury yields need not translate into a stronger dollar.
If investors begin to demand greater compensation for fiscal risk, increase currency hedges or reassess their exposure to US assets, the result could be a weaker dollar even as long-term yields rise.
In that environment, the dollar may provide less protection during risk-off periods than investors have become accustomed to expecting.
Implication for major US asset classes from midterm outcomes
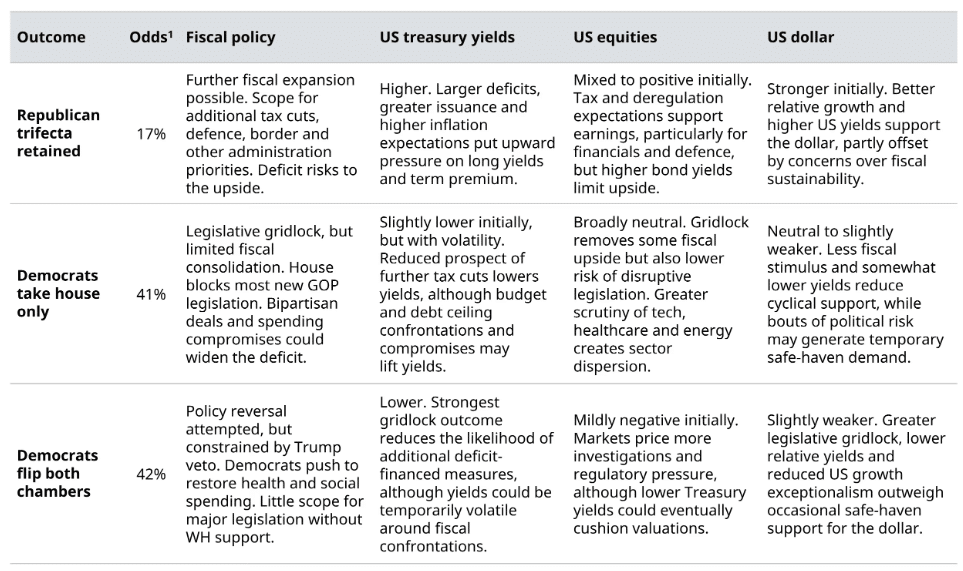
Source: Macrobond, Schroders Economics Group. August 2026
The election may be the predictable part…
Some of the post-midterm consequences are relatively easy to identify. The new Congress is likely to face a debt-ceiling standoff in mid-2027.
A compromise could increase the deficit, placing further upward pressure on long-term Treasury yields.
Democratic control of one or both chambers would increase scrutiny of politically exposed equity sectors.
Also, the greenback could lose some of its allure if investors begin to place greater weight on the risks associated with the twin deficits.
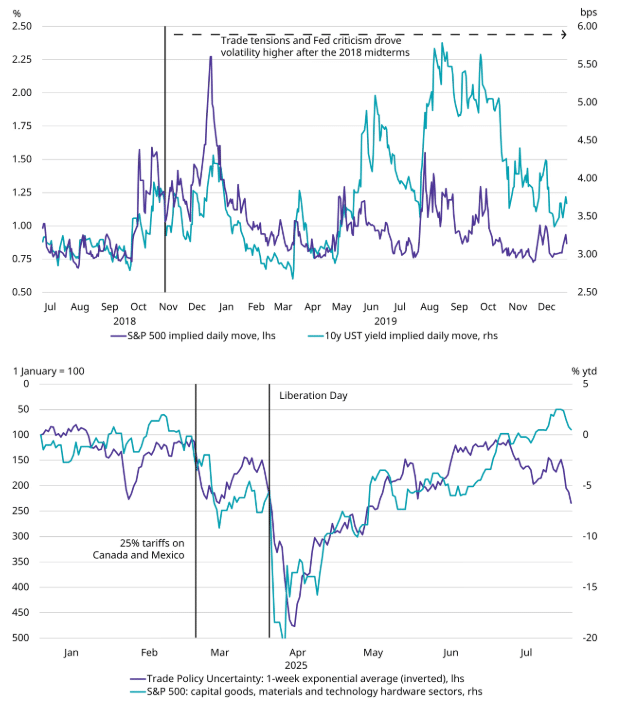
What is much harder to forecast is how President Trump will respond. Congressional constraints may see him pivot to greater use of executive authority, much as he did after Republicans lost the House in 2018.
Trade policy is the clearest example, with Trump escalating his trade dispute with China, while criticism of then Fed Chair Jerome Powell also intensified. That led to a rise in both the VIX and MOVE indices as investors braced for greater volatility in Treasuries and equities.
Taken together, this argues against viewing the midterms through the lens of directional trades. The greater risk may be a sustained increase in policy uncertainty, with consequences for Treasuries, the dollar and sector leadership within equities.
That would favour resilience over conviction: maintaining liquidity, avoiding excessive leverage and diversifying exposure across regions and currencies should leave investors better placed to absorb sudden shifts in policy.
The votes will be counted in November. Investors may still be counting the consequences years later.
Will Trump re-focus on protectionism after the midterms?
Past performance is not a reliable guide to future returns. You may not get back the amount originally invested, and tax rules can change over time. The writer’s views are their own and do not constitute financial advice.
This information should not be relied upon by retail clients or investment professionals. Reference to any particular investment does not constitute a recommendation to buy or sell the investment.
Main image: USA, anthony-shane-n5HBPCn004k-unsplash